🟢 Why nothing gets delivered after your Strategyzer workshop
Oh boy, here we go...

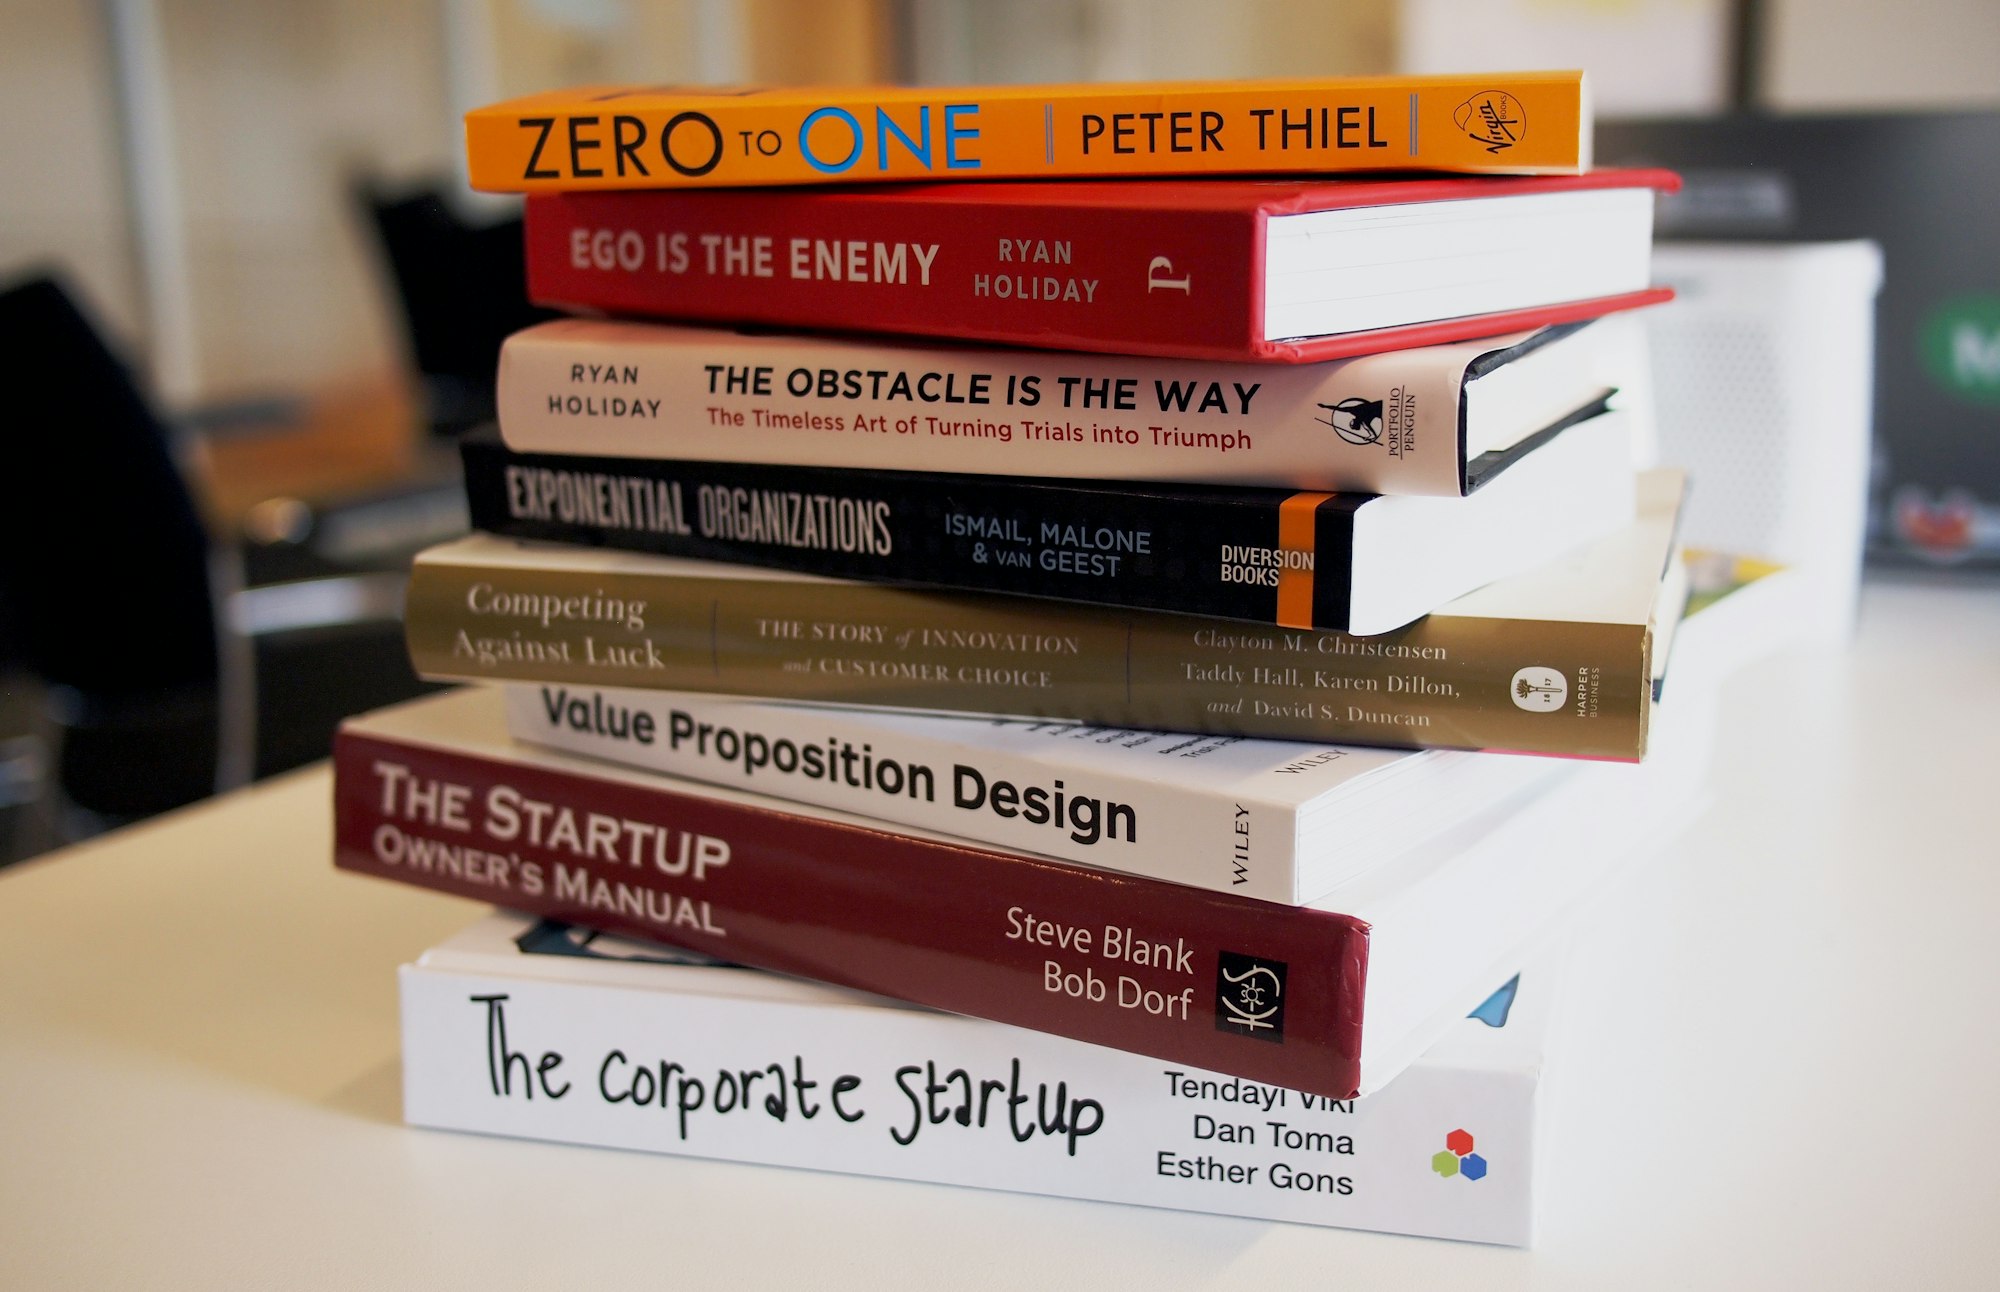
Every innovation team you know about, met or worked with, has, at some point, covered a meeting-room wall with a business model canvas and dozens of sticky notes, stepped back after a day, and felt very good about the progress made. This last part (feeling good) was possibly the only payoff.
It's difficult not to be impressed by Alexander Osterwalder and Yves Pigneur's work, in terms of sheer business generation and marketing efficiency. It also works like a religion that countless consulting and training agencies depend on. Dare criticize anything about it, and someone will immediately tell you that "you're doing ot wrong."
In practice? It plain doesn't work.
I know, I know. No one should speak ill of the mighty Business Model Canvas and its consorts, but if you had any doubt about its efficiency, I just want to let you know you're not alone.
Business models without real value analysis or pricing
One of the first things that doesn't work is that talking about money is, at best, a peripheral and long-winded process.
After about a decade of running workshops with the sole Business Model Canvas framework, without addressing much of the pricing issue in innovation, the Value Proposition Canvas appeared in 2014. It seemed the first time anyone asked to list customer jobs, pains, and gains as important. As of today, the approach is very much inspired by a design-thinking mood board, asking you what you think customers think, with little analysis of the value a company creates and can capture. Pricing, which is what makes or breaks any business model in the wild, comes late in a "Revenue Streams" box.
To be fair, before/after scenarios have been bolted to the methodology at some point, but again, talking about financial forecasts, budgetization, net present value, and more seems like a gross thing to do.
The design-thinking DNA of asking customers what they need and strictly relying on this is admittedly a core underlying issue. Customers are often unaware of the problems that matter most to them; and, in many cases, making sense of conflicting stakeholders' opinions is unrealistic.
Worse, consumer and business consumers are treated in the same way. Yet they don't value things the same way, and their metrics, biases, expectations, and decision cycles all differ. If conflating how a shopper can buy a L'Oréal serum in a few seconds, while a procurement committee at Airbus can spend months analyzing a business offer, feels wrong, well, it is.
Portfolio management and dealing with uncertainty
More recently, The Invincible Company (2020) extended Strategyzer's grip on innovation culture by discussing portfolio strategies. No doubt a big ask from industrials, it ended up splitting a genuinely chaotic and difficult reality into a neat two-sandbox framework with a catchy explore/exploit mantra.
I already explained in 2022 why it wasn't working.
Where to start? The map never specifies the levels of exploration, from adjacent extensions to markets that do not exist yet, each with its own expected return and time horizon. It doesn't explain how to spread bets and investments across them according to risk. The move from explore to exploit is seemingly left to a board of people assumed to be smarter than average. The different types of profitability you can expect from a successful project are not explained, even less so from a "failed" one. Implementing return strategies at a portfolio level (not individual projects) is swiftly put under the rug (albeit this is often where the real value creation is achieved, whether it's strategic, commercial, or internal – a new capability – years before it reaches P&L levels.
I'll grant, though, that the framework is simple enough to give innovation leaders an argument to protect exploration budgets, which is already a victory in many executive committees. Does it make life harder to implement real portfolio strategies after that? Sadly, yes as well.
But the gap I find hardest to accept is that nothing in these tools defines how much uncertainty an organization can tolerate, and at which level.
Exploring chaotic markets calls for a specific stochastic approach, with many different bets deliberately targeted across a company's blind spots, while ensuring coverage grows without budgets drifting and without exploration turning into random sampling. It is a hard discipline, just like finance or engineering, and, no, a morning post-it session won't cut it.
Innovation methods that ignore corporate culture
In the end, the thing that irks me most about this whole set of tools is something 100% of you felt when using them: a team at Airbus, whose aircraft programs run over decades under certification constraints, is supposed to see innovation and new offers exactly like a team at L'Oréal, whose surfing on market trends every month, if not weeks. Even the fact that, for instance, every successful company must become customer-driven is plain wrong.
Not factoring in the company's DNA you work with is not only absurd; it also shows a sheer lack of business acumen that is genuinely surprising. In real life, when working with a process-driven industrial group, you need to go along with the existing culture first and help it step back progressively. You sure can try and ask engineers to drop twenty years of practice and convert them into empathic designers, but don't count on them to still be "in the zone" next Monday morning when they go back to "real work".
This is one of the many reasons why even productive internal innovation units so often fail to transfer anything to the business units running in normal mode.
Effective tools and frameworks abound; they are unsexy. So what?
The thing is, tools that deal with the real complexity of innovation, changing business models, or scouting chaotic zones of the market abound. They've been created between the late 1970s and the mid-1990s, when the economy in the West was largely industrialized, and several systemic shocks had already been encountered.
I'll never tire of reminding innovation practitioners of Pierre Wack's scenario planning at Shell, which was a Copernican moment for business thinking facing major uncertainties (what if you can't business model and then business plan your way out of market turbulences?). Real options thinking, from Stewart Myers in 1977 to Rita McGrath and Ian MacMillan's discovery-driven planning in 1995, puts an explicit value on optionality, which is precisely the question of acceptable uncertainty the explore/exploit map doesn't even consider.
Are these books fun to read, or are these frameworks easy to explain in five minutes during your next executive committee presentation? No.
So f#%$ing what?
Would you feel comfortable with your finance department being run the way most run their innovation department? Imagine hiring juniors from a marketing background, telling them financial reporting can be learned "on the job," giving them a few colorful books and a bunch of Post-its, while cheerfully adding that, since it is late September, everyone trusts them to produce an impeccable Q4 and FY 2026 reporting.
That's the problem I have with Strategyzer. Making our profession dumb for the sake of making it look accessible. If it were so easy, I doubt so many industries would be so unsuccessful at innovating to literally save their lives...
The case for training wheels?
It's not the first time I've written about Business Model Generation and the follow-up tools, which grew out of Osterwalder's doctoral work at the University of Lausanne and was published by Wiley in 2010. For years, I tried to see some value in it, just like starting biking with training wheels. Learn slowly, get your balance, and then forget about it as fast as possible. No need to be embarrassed.
Except that more than ever, markets in 2026 look much more like a steep mountain trail taken at speed under a hail storm with hungry bears running after you. Not only do we need to remove the training wheels, but we simply can't afford to reproduce the same mistakes over and over again with ill-fitted equipment.
All this being said, I'm not weighing anything like Strategyzer, nor do I have the brand presence they have, and certainly not the same broad trust they can command. Which also means I don't have much pressure either to work with as many companies as I can across several continents each year.
This is freedom.
Freedom to work with businesses that just don't need to "step back and reassess" or want to have a "blue-sky session" during an "offsite". Freedom to prioritize businesses that need things done in the tumultuous context of both market and technical disruptions we endure.
Need to talk? Feel free to reach out... ; )
More about this:
 Philippe MEDA
 Philippe MEDA
 Philippe MEDA
 Philippe MEDA